HDB Upgraders: Will They Be Able to Afford Your Condo?
For many mass-market and suburban condos, HDB upgraders can form an important part of the future buyer pool. The key question is not simply whether their HDB has appreciated, but how much usable equity, CPF, income and borrowing capacity they may actually have when you want to sell.
A higher HDB selling price does not equal the same amount of cash for the next condo. Test the upgrader’s usable proceeds, CPF position, financing capacity and upgrade gap.
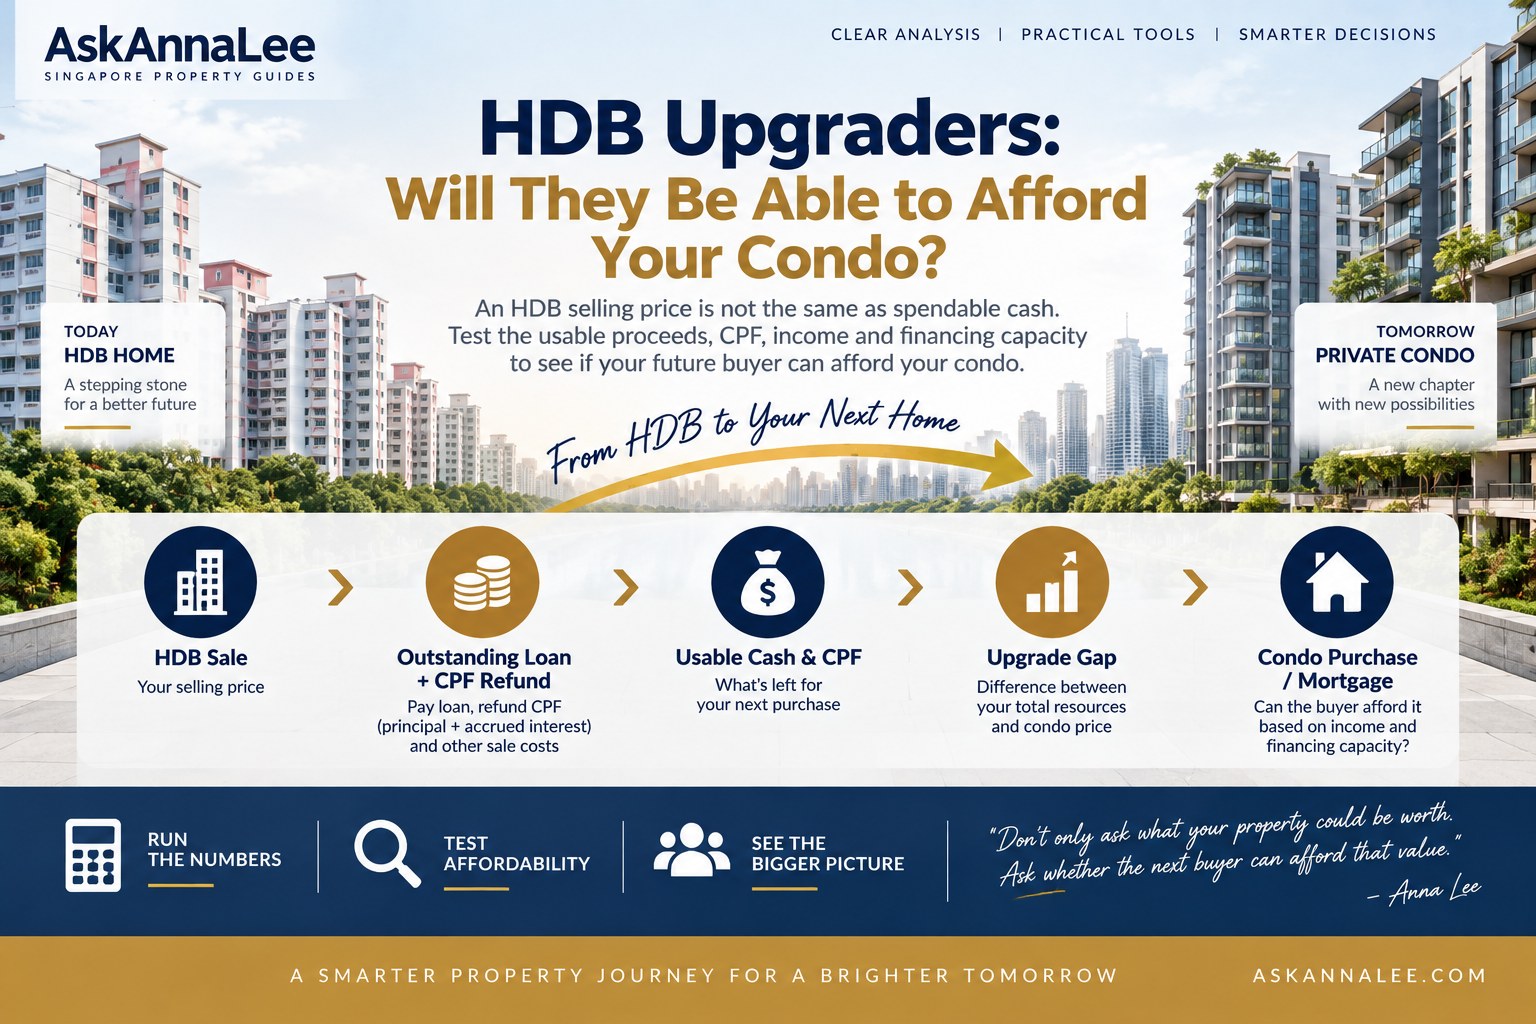
HDB upgrader demand is not determined by the HDB selling price alone. What matters is the household’s usable proceeds after sale, CPF position, upgrade gap and borrowing capacity when your condo becomes their next purchase.
Quick Answer
Test an HDB upgrader from the sale proceeds forward. The HDB selling price first has to deal with the outstanding housing loan, required CPF refund and sale expenses. The household then needs enough cash and CPF for the condo purchase, stamp duties and a prudent buffer, while also qualifying for the required mortgage.
That means your future condo exit price should be tested against the upgrader’s upgrade gap: the difference between the resources available after selling the HDB and the total cost of buying your condo.

Work from the upgrader’s resources forward. Your future selling price has to fit what a realistic HDB upgrader can fund with sale proceeds, usable CPF and a sustainable mortgage.
HDB Value Is Only the Starting Point
A buyer who sells an HDB flat for a strong price does not automatically receive the full amount as spendable cash. CPF Board states that sale proceeds are generally applied first to the outstanding housing loan, then the required CPF refund, followed by other sale expenses. The refunded CPF remains the owner’s money, but its availability and destination depend on CPF rules and the owner’s circumstances.
Do not estimate upgrader demand from HDB resale prices alone. Estimate the household’s net resources after sale, then test the mortgage and total condo quantum they would need to bridge.
Step 1: Estimate What the HDB Sale Actually Releases
Start with a realistic HDB sale price. Deduct the outstanding housing loan and allow for sale expenses. Then account for the CPF housing refund. CPF Board states that the required refund is generally the CPF principal used plus accrued interest; additional rules can apply for owners aged 55 and above.
Keep cash proceeds and CPF refund separate. CPF refunded to the owner is not a transaction loss, but it is also not automatically identical to cash available in a bank account.

The HDB sale price is only the starting figure. Separate outstanding loan repayment, CPF refund, sale expenses and usable resources before estimating what can move into the condo purchase.
Step 2: Measure the Upgrade Gap
Next, compare the household’s usable cash and CPF resources with the condo’s total purchase cost. Include the downpayment, Buyer’s Stamp Duty and any applicable Additional Buyer’s Stamp Duty, plus legal and moving costs and a sensible financial buffer.
For Singapore Citizens, IRAS currently imposes no ABSD on a first residential property, while a second residential property generally attracts 20% ABSD. The buyer’s actual property count and eligibility for any remission therefore matter greatly to the upgrade calculation.
Step 3: Test Whether Income Can Support the Mortgage
The remaining gap usually has to be financed. Current MoneySense guidance states a 55% TDSR threshold for total monthly debt commitments. Bank-loan LTV limits also depend on factors including outstanding housing loans, loan tenure and age.
Do not assume the upgrader will borrow to the regulatory maximum. Stress-test the monthly mortgage at a prudent rate and ask whether the household would still choose your condo when other new-launch and resale alternatives are available at a lower quantum.

Your exit is stronger when the required condo quantum can be supported without stretching the upgrader’s upfront resources or mortgage capacity to unrealistic levels.
8 Checks Before an HDB Upgrader Can Support Your Exit
Use all eight checks together. A high HDB resale price does not automatically create enough buying power for your condo. Test what the household can actually bring forward after the HDB sale and what it can sustainably finance next.
What is a realistic selling price for the HDB flat when you expect the upgrader to enter the condo market?
How much of the HDB sale proceeds would first be needed to clear the remaining housing loan?
How much CPF principal and accrued interest may need to be refunded, and how much CPF could remain usable for the next home?
After the loan, CPF refund and sale expenses, what cash and usable CPF resources can actually support the condo purchase?
What is the difference between those usable resources and the total upfront cost of buying your condo?
Can household income and existing debts support the mortgage needed to bridge that upgrade gap?
At the same total quantum, what new-launch and resale alternatives will the upgrader be able to choose instead?
Is the selling price you need still realistic once the upgrader’s usable resources, financing and alternatives are considered?
How to Read the Result
Exit Quantum Looks Supportable
The upgrader’s sale resources, CPF position and mortgage capacity can reasonably bridge into your required selling price.
Upgrade Gap Needs Stress-Testing
The purchase may be financeable, but the upgrader would need to use a large share of available resources or borrowing capacity.
Sale Proceeds Are the Constraint
Income may support the mortgage, but the HDB sale does not release enough usable cash and CPF to cover the required upfront purchase costs comfortably.
Your Exit Quantum Looks Stretched
The required selling price creates an upgrade gap that is difficult to support after realistic sale proceeds, financing and competing condo choices are considered.
Test the Upgrade Gap Before You Set Your Exit
Estimate what the upgrader can bring forward from the HDB sale, then test whether a sustainable mortgage can bridge the household to your required condo quantum.
01 · FINANCINGTest Mortgage & Affordability →02 · EXITTest Your Required Exit Price →
Sources & Verification
Use current official Singapore sources when applying the HDB upgrader framework. HDB resale transaction data helps establish realistic sale proceeds; CPF Board guidance explains CPF housing refunds and subsequent housing use; MoneySense/MAS guidance is relevant to mortgage affordability and TDSR; and IRAS publishes prevailing BSD and ABSD rules.
HDB — Resale transaction prices →
CPF Board — CPF refund when selling property →
MoneySense — Buying a property: how much can you afford? →
IRAS — Stamp duty for property buyers →
Method note: The framework estimates buyer capacity rather than predicting a specific household’s behaviour. Actual sale proceeds, CPF availability, loan eligibility, duties and purchase choices depend on the buyer and prevailing rules at the time.
Educational disclaimer: This guide is for general educational and research purposes. It is not legal, tax, financial, lending or investment advice. HDB sale proceeds, CPF refunds, loan eligibility, duties and property suitability depend on the household’s circumstances and prevailing rules.